
7 Powerful FRS 102 Lease Accounting 2026 Changes for UK Businesses
For many UK businesses, 2026 may feel comfortably distant. In accounting terms, however, it is right around the corner. Significant updates to Financial Reporting Standard 102 are approaching, and FRS 102 lease accounting 2026 reforms will fundamentally alter how many companies present their financial position on balance sheets.
These updates are far from cosmetic. They will reshape balance sheets, affect reported profitability, and potentially influence bank lending decisions long before the first set of revised accounts is filed.
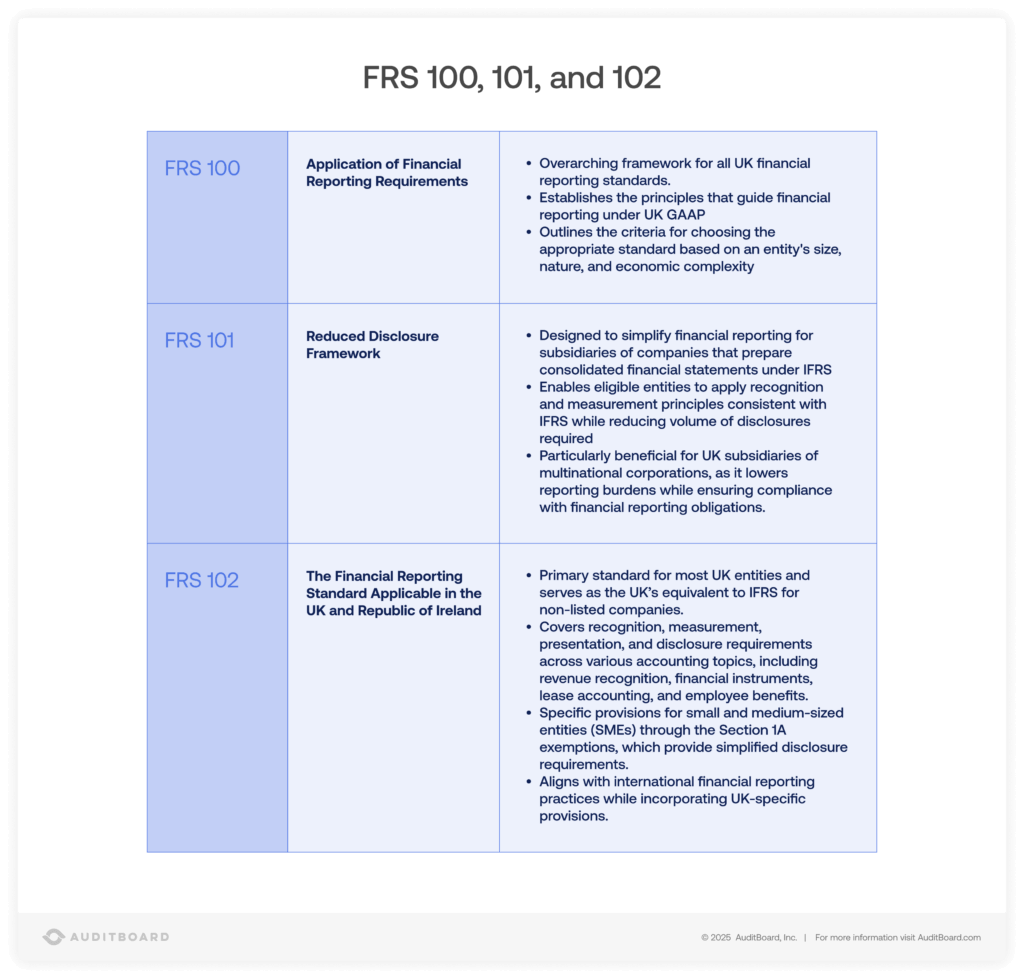
According to official accounting guidelines published by the Financial Reporting Council (FRC), these Periodic Review amendments align UK GAAP more closely with international reporting frameworks like IFRS 16.
Lease Accounting Is About to Look Very Different
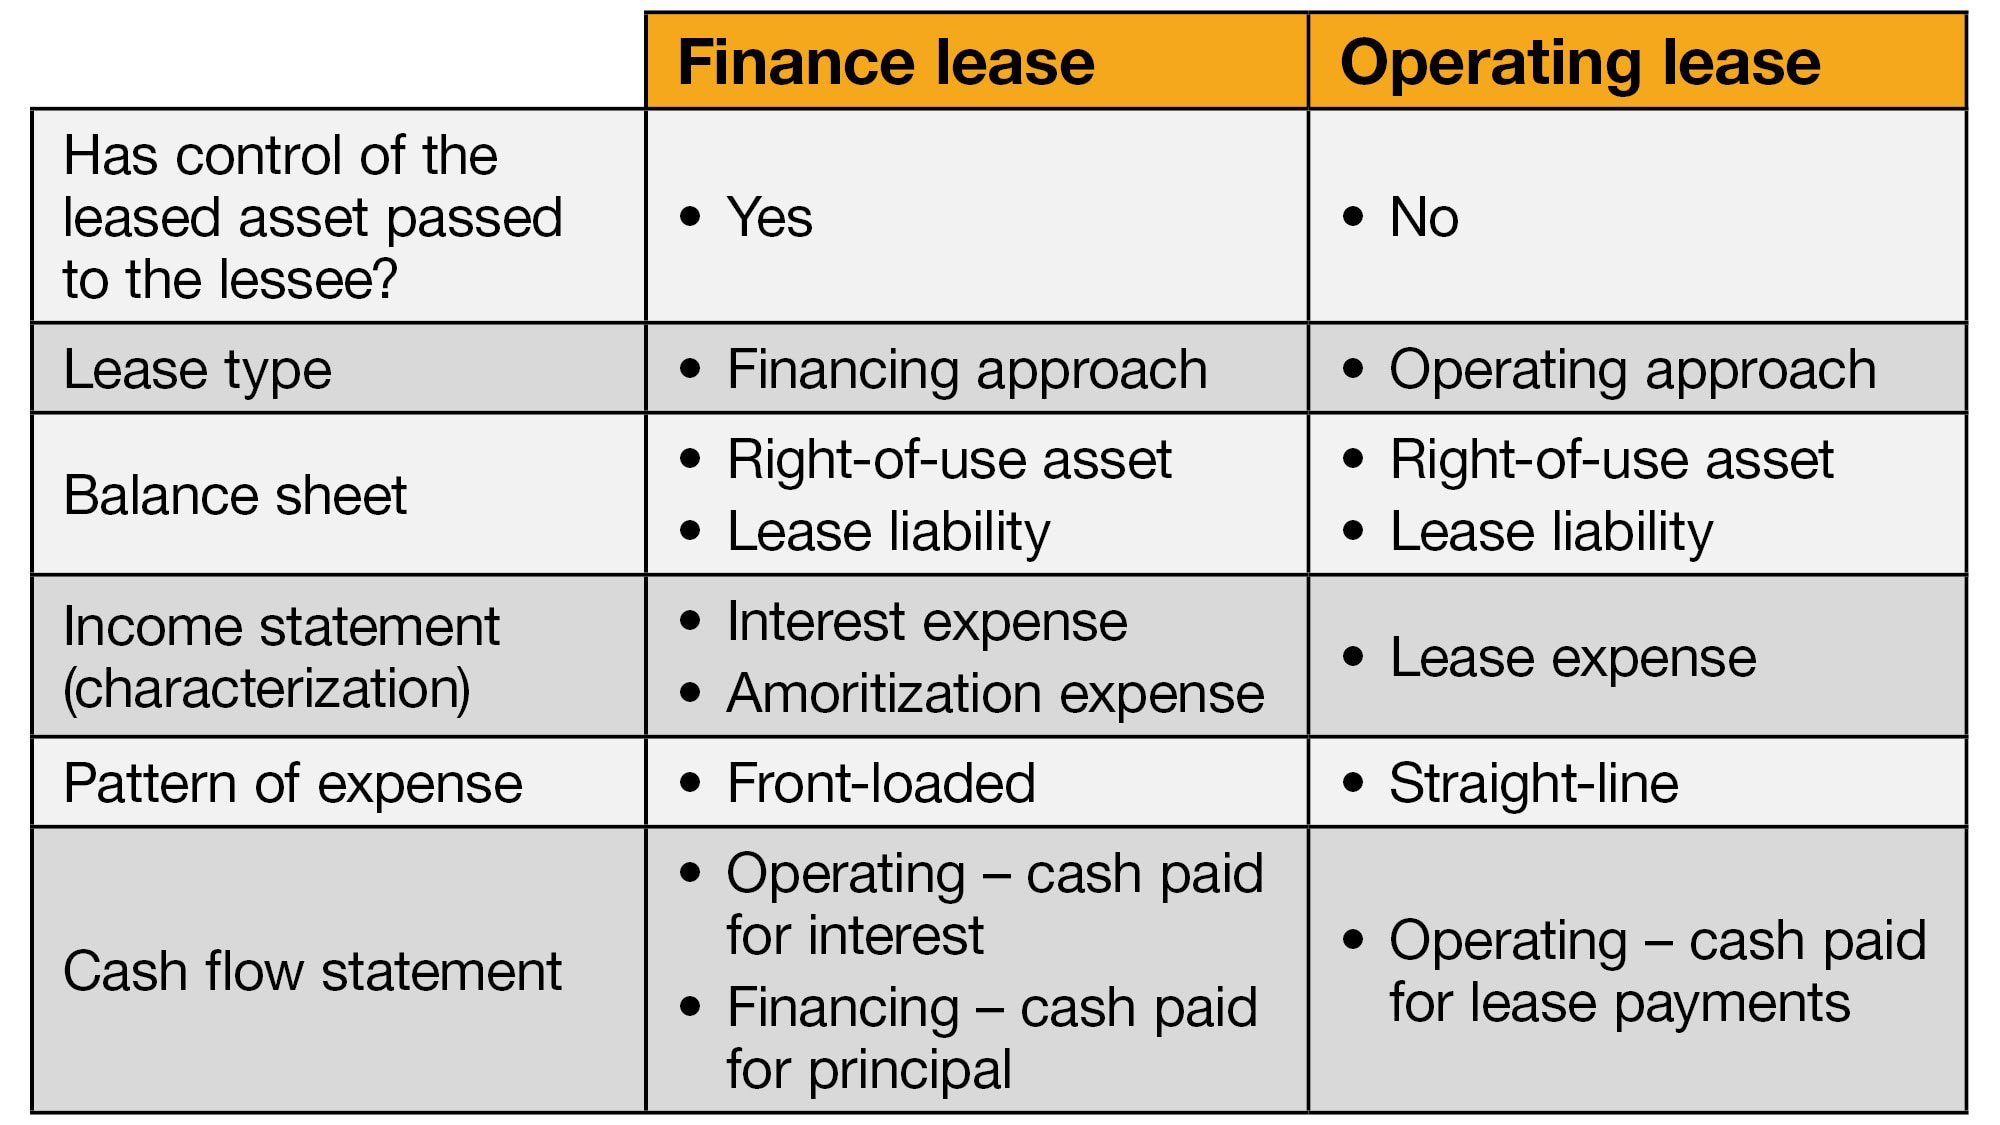
One of the most impactful changes relates to lease accounting. Arrangements that previously sat quietly off the balance sheet will soon be brought firmly into view.
Under the revised approach, most leases will give rise to:
-
A recognised right-of-use asset, and
-
A corresponding lease liability
For businesses that rely heavily on property, vehicles, or equipment leases, this will result in a noticeable expansion of the balance sheet — even though cash flows remain unchanged.
The accounting presentation will shift, but the commercial consequences could be very real.
What Is the FRS 102 Lease Accounting 2026 Update?
At its core, FRS 102 lease accounting 2026 brings operating leases directly onto the balance sheet for medium and large UK entities. Previously, operating lease commitments sat off-balance-sheet in financial notes.
Under the revised framework, almost all leases will require recognizing:
-
A recognized Right-of-Use (ROU) Asset representing the right to use the underlying property, vehicle, or equipment.
-
A corresponding Lease Liability representing the discounted obligation to make future lease payments.
For businesses that rely heavily on leased offices, commercial premises, vehicle fleets, or machinery, this will result in a noticeable expansion of the balance sheet — even though underlying cash flows remain completely unchanged.
The Knock-On Effect for Key Financial Metrics
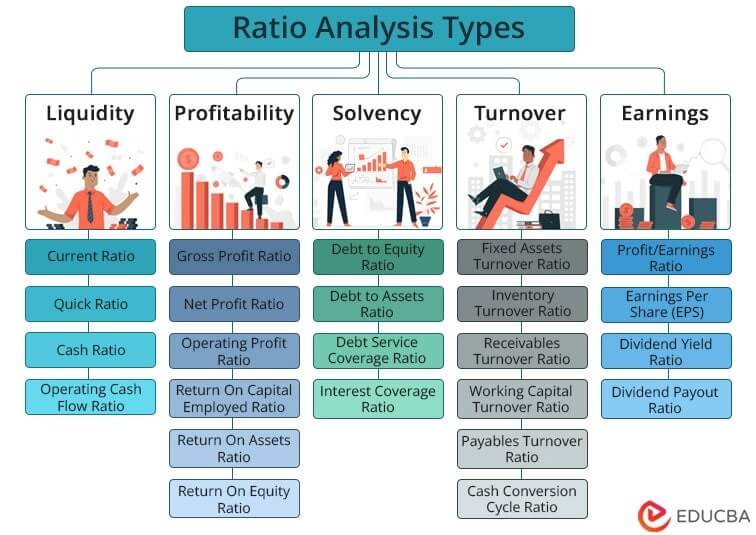
When new liabilities appear on the balance sheet, financial ratios change automatically. Gearing increases. EBITDA calculations shift. Profit profiles can become more front-loaded due to the way depreciation and interest are recognised.
For some businesses, this could:
-
Push gearing ratios beyond lender comfort zones
-
Trigger covenant discussions
-
Affect perceptions of financial strength among stakeholders
Crucially, none of this reflects a deterioration in the underlying business. But accounting numbers shape decisions, and those decisions are often made by banks, investors, and counterparties who rely on reported figures.
Why Early Planning Matters More Than Ever

The most significant risk surrounding the 2026 changes is not the technical complexity — it is late engagement.
Businesses that wait until implementation will be forced into reactive conversations with lenders and stakeholders. Those that act early can model the impact, explain changes clearly, and renegotiate terms from a position of control rather than urgency.
This is where accounting shifts from compliance to advisory. Understanding how future standards affect today’s decisions allows businesses to manage expectations and protect commercial relationships.
Data Readiness Is the Hidden Challenge
Before any calculations can take place, businesses need clarity on their lease arrangements — and that is often harder than it sounds.
Agreements may be scattered across systems, emails, or paper files. Terms such as renewal options, break clauses, and variable payments all affect measurement and must be identified accurately.
Getting organised now avoids rushed assumptions later and ensures that financial reporting reflects reality rather than estimates made under pressure.
Turning a Reporting Change into a Strategic Advantage
While the upcoming changes will require effort, they also create an opportunity.
Businesses that understand their lease commitments in detail gain better insight into long-term cost structures, operational flexibility, and financing exposure. That knowledge can support better decisions around property strategy, investment, and funding.
Handled well, the 2026 changes become a catalyst for stronger financial discipline — not just a compliance exercise.
7 Critical Impacts of FRS 102 Lease Accounting 2026 on Your Business
Understanding how these accounting shifts impact your commercial operations is essential for proactive planning:
1. Off-Balance-Sheet Leases Are Brought into View
Arrangements that previously sat quietly in disclosures will now be brought firmly onto the main balance sheet, increasing recognized assets and debt obligations simultaneously.
2. Automatic Shift in Key Financial Ratios
When new liabilities appear on the balance sheet, key metrics change automatically. Financial gearing increases, net debt expands, and interest cover calculations shift.
3. Impact on Lender Covenants and Financing
For some businesses, expanded balance sheet debt could:
-
Push gearing ratios beyond bank lender comfort zones.
-
Trigger potential debt covenant breaches.
-
Alter perceptions of creditworthiness among external stakeholders.
Crucially, none of this reflects a deterioration in underlying business operations, but accounting figures shape lender decisions.
4. Profit Recognition Profiles Change
Because lease expenses will now be split into asset depreciation and interest expenses, profit profiles can become more front-loaded. While operating profit (EBITDA) may appear higher, early-year net profits may be reduced.
5. Data Readiness Is the Hidden Challenge
Before calculations occur, businesses need total clarity on existing lease contracts. Scattered lease files, break clauses, renewal options, and variable rent reviews must be accurately audited and centrally cataloged.
6. Shifting Focus from Compliance to Advisory
Early modeling of FRS 102 lease accounting 2026 changes shifts your accounting from basic compliance to proactive advisory. Businesses that act early can renegotiate loan terms and manage stakeholder expectations from a position of control.
7. Strategic Advantage in Property and Asset Management
Companies that gain detailed visibility into long-term lease commitments improve their cost structures, operational flexibility, and capital allocation. Handled effectively, these changes become a catalyst for disciplined financial management.
To explore how modern accounting standards affect your business structure, consult our comprehensive UK Accounting Services Guide or read about our approach to digital finance in our Accounting Automation article.
Final Thoughts: Accounting Changes That Demand Commercial Thinking

FRS 102 is evolving, and the impact will extend well beyond the accounting department. The challenge for UK businesses is not simply to comply, but to understand what the numbers will say — and how banks, investors, and suppliers will interpret them.
At Ten Piece Limited, we help businesses anticipate regulatory shifts rather than react to them — combining technical expertise with commercial insight to ensure your accounts support confident decision-making.
Learn more about our team on our About Us page, explore our full suite of Services, or Contact Us today to model your lease accounting transition.