

Choosing an accountant for your limited company is an important business decision. The right accountant can help you maintain accurate financial records, prepare statutory accounts, meet tax filing deadlines and understand your company’s financial position.
However, not every accountant offers the same services. Some focus mainly on preparing annual accounts and tax returns, while others provide ongoing bookkeeping, VAT, payroll and business advice.
If you are setting up a new limited company, already trading or considering changing your accountant, it is important to find a professional who understands your company’s requirements and provides the right level of support.
So, how do you find a good accountant for your limited company in the UK?
1. Expert Answer: What Should You Look for in a Limited Company Accountant?
A good limited company accountant should have the relevant technical knowledge, understand your business activities, communicate clearly, and explain exactly what their services include.
Here are the key areas to assess before making your decision.
A. Check professional qualifications and practice authorisation
Start by checking the accountant’s qualifications and the practice’s regulatory position.
Recognised UK accountancy and tax bodies include:
- Association of Accounting Technicians (AAT).
- Association of Chartered Certified Accountants (ACCA).
- Institute of Chartered Accountants in England and Wales (ICAEW).
- Chartered Institute of Management Accountants (CIMA).
- Chartered Institute of Taxation (CIOT).
Ask which professional body the accountant belongs to, whether the practice holds the relevant licence or practising permissions, and which organisation supervises its anti-money laundering obligations.
These are separate matters. Membership of a professional body does not automatically establish that a practice has every permission required for the services it provides.
You can check relevant credentials through the professional body’s official website or by requesting confirmation from the practice.
B. Make sure they understand limited company accounting
A limited company has accounting and reporting responsibilities that differ from those of a sole trader.
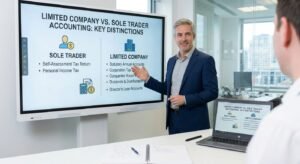
Your accountant should understand matters such as:
- Statutory annual accounts.
- Corporation Tax computations and CT600 returns.
- Companies House filing requirements.
- Bookkeeping and bank reconciliations.
- Director remuneration and dividends.
- Director’s loan accounts.
- VAT registration and returns, where applicable.
- PAYE and payroll, where applicable.
- Confirmation statements and company information changes.
For example, a director who withdraws money from the company cannot automatically treat every withdrawal as a salary or dividend. The transaction needs to be recorded and treated correctly, taking account of the company’s records, available distributable profits, payroll obligations and any director’s loan balance.
A knowledgeable accountant should be able to explain these distinctions before they create problems.
C. Check whether they understand your business model
Two limited companies can have very different accounting requirements.
A small consultancy might have a few invoices and expenses each month. A restaurant, construction company or online retailer may have higher transaction volumes, VAT considerations, employees, stock or industry-specific reporting issues.
Ask whether the accountant has experience with businesses similar to yours.
You should explain:
- What your company does.
- How it earns revenue.
- How many transactions it processes.
- Whether it is VAT registered.
- Whether it employs staff.
- Whether it has one or several directors.
- Whether it sells products, provides services or operates online.
- Whether you need regular financial reports or tax planning support.
The more clearly the accountant understands your business, the easier it is to agree on an appropriate service.
D. Understand exactly what is included in the accounting fee
One of the most important questions to ask is:
What will you actually do for my company, and what will I have to pay extra for?
An accounting package might include annual accounts and a Corporation Tax return but exclude bookkeeping, VAT returns, payroll and personal tax returns.
A different package might provide ongoing bookkeeping, quarterly VAT returns, payroll and regular accounting support.
Before accepting a quotation, ask whether the following services are included:
| Service | What to clarify |
|---|---|
| Bookkeeping | Transaction volume, frequency and bank reconciliations |
| Annual accounts | Preparation and Companies House filing |
| Corporation Tax | Tax computation, CT600 preparation and submission |
| VAT | Registration advice, return preparation and submission |
| Payroll | Number of employees and frequency of payroll |
| Director’s Self Assessment | Whether personal tax returns are included |
| Tax advice | Whether routine advice or planning is included |
| Software | Whether Xero or other software is included or charged separately |
| Management accounts | Whether monthly or quarterly reporting is available |
Request a written quotation that clearly identifies the scope, exclusions and additional charges.
E. Check whether the accountant manages important deadlines
Limited companies have several filing and payment obligations.
For example, under the usual Companies House timetable:
- A private company generally has nine months after the end of its financial year to file its annual accounts.
- A company must generally file its Corporation Tax return within 12 months of the end of its accounting period.
- Corporation Tax is usually payable nine months and one day after the end of the accounting period for companies outside the quarterly instalment payment regime.
These are different deadlines. Filing a Corporation Tax return and paying the Corporation Tax are separate obligations.
Your accountant should help you understand the deadlines relevant to your company and agree how information will be collected in time.
However, appointing an accountant does not transfer the directors’ legal responsibilities to that accountant. Directors remain responsible for ensuring that the company meets its statutory obligations.
F. Choose an accountant who communicates clearly
A good accountant should not simply prepare documents and send them to you for approval without explanation.
You should be able to ask questions about:
- How much Corporation Tax your company may need to pay.
- Whether a transaction is a business expense.
- How to record money withdrawn by a director.
- Whether VAT registration is required.
- How to pay yourself from the company.
- Whether the company can afford to employ someone.
- How much cash should be retained for upcoming liabilities.
Ask who will be your main contact, how you can submit documents and what response times you can reasonably expect.
Clear communication is particularly important when a tax deadline or financial decision is approaching.
G. Consider cloud accounting and remote support
A good accountant does not necessarily need to be located in the same area as your company.
Cloud accounting software such as Xero can help directors and accountants access financial records, reconcile transactions and monitor business performance.
Before choosing a cloud-based service, establish:
- Which accounting software will be used.
- Who is responsible for maintaining the records.
- How often the bookkeeping will be updated.
- How documents will be shared securely.
- Whether the accountant reviews the records regularly.
- Whether software subscriptions are included in the fee.
Remote accounting can work effectively when responsibilities, communication and document handling are properly organised.
2. Common Mistakes When Choosing an Accountant for a Limited Company
Choosing the cheapest quotation
A low annual fee may cover only statutory accounts and a Corporation Tax return. If you also need bookkeeping, VAT and payroll, the additional charges may make the overall service more expensive.
What to do: Compare quotations using the same list of required services.
Assuming the accountant will handle everything
Some directors believe that appointing an accountant means they no longer need to monitor filing deadlines or maintain business records.
That is incorrect. Directors retain legal responsibilities, even when professional advisers assist with compliance.
What to do: Agree who is responsible for each task and how the accountant will obtain information from you.
Not providing complete financial records
Missing invoices, incomplete bank records and unrecorded director withdrawals can make it difficult to prepare accurate accounts.
What to do: Maintain organised records and provide the accountant with complete information.
Treating personal and company money as interchangeable
A limited company is a separate legal entity. Company funds should not be treated as the director’s personal money.
Personal expenditure paid by the company and money withdrawn by a director must be recorded and treated correctly.
What to do: Ask your accountant how to record director withdrawals, expenses, salary and dividends.
Ignoring the engagement letter
A verbal agreement about fees and services can lead to disputes.
What to do: Read the engagement letter carefully. Check the scope of work, fees, additional charges, responsibilities, payment terms, and termination arrangements.
Waiting until the filing deadline to find an accountant
Leaving your accounting arrangements until shortly before the accounts or tax return deadline can create unnecessary pressure.
What to do: Appoint an accountant early and establish a regular process for submitting records.
3. Practical Recommendations: How to Find the Right Accountant
Use this process before appointing an accountant for your limited company.
Step 1 – Identify your requirements
List the services your company needs. Consider bookkeeping, annual accounts, Corporation Tax, VAT, payroll, director’s Self Assessment, and ongoing advice.
Step 2 – Shortlist suitable accounting practices
Look for practices with experience supporting limited companies of a similar size and type. Check their professional credentials and service offering.
Step 3 – Arrange an initial discussion
Explain how your business operates, your transaction volumes, VAT position, number of employees and the support you expect.
Step 4 – Request a written quotation
Ask for a breakdown of the services included, the annual or monthly fee, software charges and additional work rates.
Step 5 – Establish the working arrangements
Confirm who will handle your accounts, how often bookkeeping will be updated, how documents will be exchanged and how deadlines will be monitored.
Step 6 – Review the engagement letter
Ensure the agreement reflects the quotation and clearly sets out the responsibilities of both parties.
Step 7 – Appoint your accountant before problems arise
Do not wait until a filing deadline is approaching or an HMRC query has already become urgent. Good accounting support is most effective when it is organised throughout the year.
4. When Should You Change Your Existing Accountant?
It may be time to review your current accounting arrangements if:
- You regularly struggle to receive responses.
- You do not understand what your accounting fees cover.
- You receive unexpected additional charges.
- Your bookkeeping and accounts are consistently delayed.
- You are not receiving explanations of your company’s financial position.
- Your business has grown but your accounting support has not developed with it.
- You need services that your current accountant does not provide.
Changing accountants is possible, but it should be managed properly. You should establish the current filing position, outstanding work, access to accounting records, and any professional handover requirements before the transition.
Ten Piece Limited – The Trusted Accounting Partner
Ten Piece Limited is licensed and regulated by the AAT (License No. 1009076) and supervised under HM Treasury Money Laundering Regulations. Ten Piece Limited – The Trusted Accounting Partner. Based in London, we provide professional accounting, taxation and business advisory services to individuals, sole traders, entrepreneurs, start-ups, company directors and businesses across London, Greater London and throughout the UK. Our services include bookkeeping, VAT registration and returns, payroll management, annual accounts, Corporation Tax returns, Self Assessment, tax planning, financial reporting and Xero accounting support. We believe everyone deserves access to professional accounting advice, regardless of their income, occupation, financial circumstances or source of earnings. Whether you run an established company, are starting your first business, work as a freelancer, earn through content creation or have multiple income streams, our approachable and non-judgemental team is here to listen, understand your circumstances and provide practical, tailored advice. We pride ourselves on being easy to talk to, offering clear guidance and treating every client’s personal and financial information with the utmost confidentiality and discretion, subject to applicable legal and regulatory obligations. Whether you are looking for a reliable accountant in London, affordable accounting services for your limited company, better bookkeeping support, professional tax advice or a new accountant who genuinely understands your needs, Ten Piece Limited is here to help. Contact us today for a personalised quotation and discover accounting support built around you and your business.
Ready to Find the Right Accountant for Your Limited Company?
Ready to simplify your accounting processes and optimize your tax strategy? Contact Ten Piece Limited today at +44 20 8050 5527, email hello@tenpiece.co.uk, or visit tenpiece.co.uk to request a customized quote or schedule a consultation with our expert team.